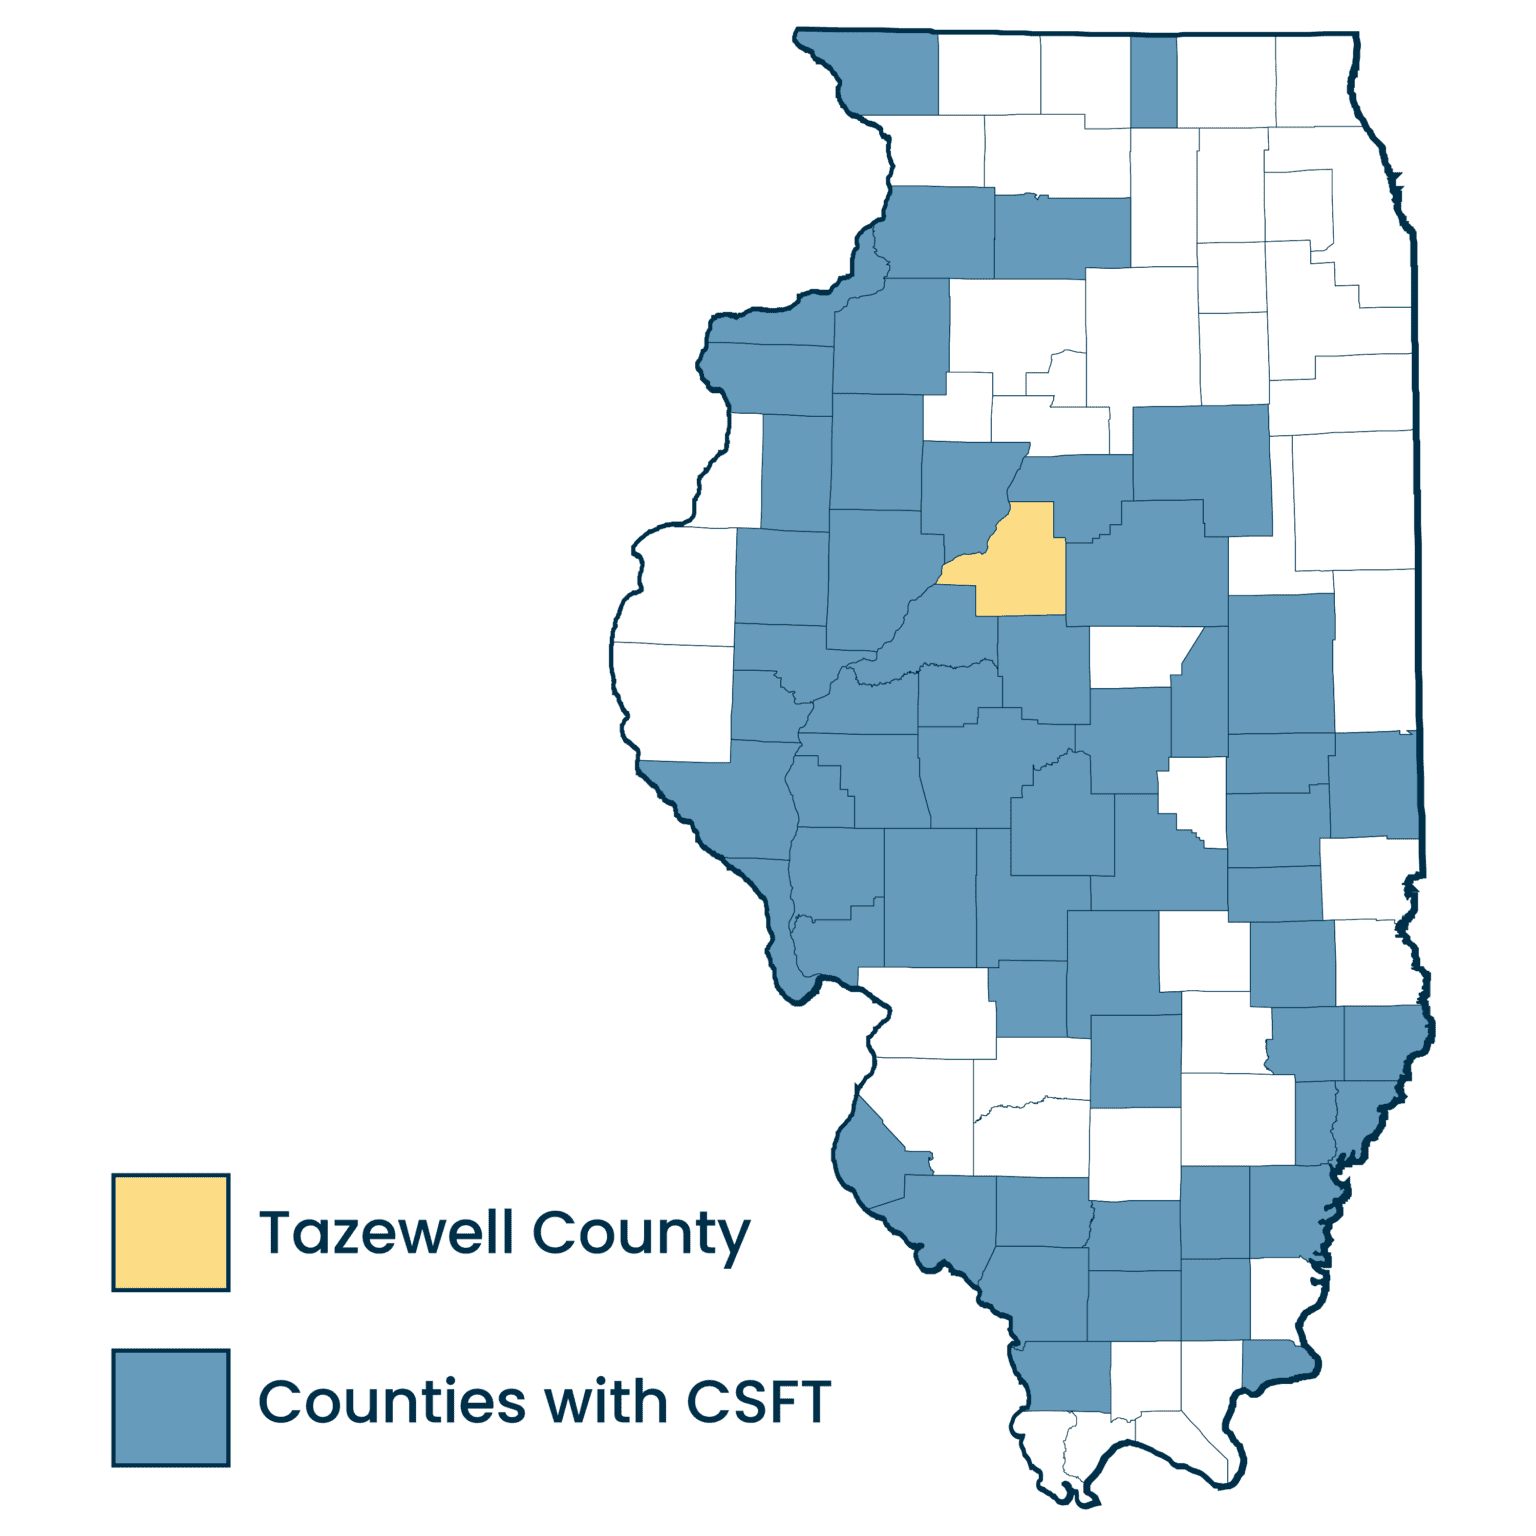
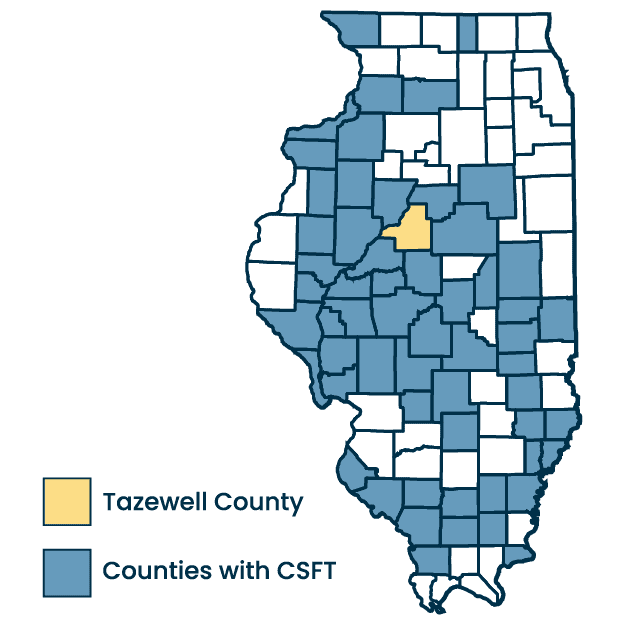
The Illinois County Schools Facility Sales Tax (CSFT) is a 1% sales tax option, commonly known as a one-cent tax, available to Illinois voters since 2007. If approved, it can make sales tax revenue (Public Act 97-0542) available for school districts. Since 2007, nearly 60% of Illinois counties have approved a CSFT, including surrounding counties such as McLean, Peoria, Woodford, Fulton and Mason.
If approved, one cent per dollar spent would be applied to qualifying purchases made within the county to support public schools. For example, on a $1.00 purchase, one cent would be added to the price for qualifying purchases. Items that are not currently taxed under Illinois law, are not taxed under the County Schools Facility Tax.
This sales tax is estimated to cost a family of four an average of $3.38 per week and $14.67 per month.
This is based on 2023-2024 data from the U.S. Bureau of Labor Statistics that covers spending trends on qualifying purchases in the Peoria region. It would vary depending on purchasing habits and number of residents in a household.
Here are some examples of what the tax would cost on common, qualifying purchases:
- A coffee at Starbucks $5 = .05 cents
- Laptop at Best Buy $500 = $5.00
- Book purchase on Amazon $5 = 5 cents
- T-shirt at Target $20 = 20 cents
- Bag of apples at Kroger $5 = No increase
- Medicine = No increase
The revenue generated from this tax would provide:
Facility maintenance and upgrades: Funds can be used for necessary repairs and upgrades to school buildings and facilities, including HVAC systems, parking lots, and other general maintenance. These improvements ensure that our schools remain safe, up to code, and equipped to meet the needs of today’s students.
Safety and security needs and supports: The revenue raised through this tax can directly support school security needs, such as surveillance systems, secure entry points, and School Resource Officers. Additionally, this revenue could be applied to expanding access to mental health professionals and resources for students.
Possible bond abatement: To the extent a district uses this sales tax revenue to pay building bond debt, state law requires a matching reduction in the property taxes levied for those bonds. The amount of any property tax impact depends on how each district applies the revenue. In addition, school districts that receive county facility sales tax revenue can rely less on property taxes to fund facility costs.
Projects would be delayed with repair and maintenance costs likely increasing. School districts would be faced with considering alternative options, such as property tax increases, to fund essential facility improvements and safety and security needs.
Under Illinois law, a countywide sales tax for school facilities can be imposed only if voters approve it, so the question is on the November 3 ballot for Tazewell County voters to decide. Many school buildings in the county were built in earlier eras and need updates to meet current safety and learning standards, and districts face rising operating costs.
It is estimated to generate about $22 million per year countywide. Based on a 2026 analysis prepared for the County by PGAV Planners, nearly 60% of taxable retail spending in Tazewell County is projected to come from visitors from outside the county.
Only items that are currently subject to sales tax will be subject to this tax. Some items are exempt.
Example purchases that would be taxed include:
- Coffee at Starbucks ($5) = 5 cents
- Laptop at Best Buy ($500) = $5.00
- T-shirt at Target ($20) = 20 cents
Items that are not currently taxed under Illinois law, are not taxed under the County Schools Facility Tax. Items not subject to this tax include:
- Groceries
- Over the counter medicine and prescription drugs
- Cars, trucks, ATV’s boats, RV’s, mobile homes
- Farm equipment, parts, inputs
- Services (accounting, legal, etc.)
- Wholesale level purchases
Funds from the tax may not be used for staff salaries and benefits*, instructional supplies, books, computers, buses, or other operating expenses.
(*Recent changes in Illinois CSFT law allow schools to use these funds only for salaries/benefits for School Resource Officers and/or Mental Health Professionals)
Revenues from this sales tax would remain under local control, not state control. Each school district’s Board of Education determines how to allocate the funding within the state’s guidelines.
Yes. Every school district in the county would benefit. This tax revenue would be collected from all cities and townships in the county and distributed to school districts based upon student enrollment.
Revenue is distributed based upon the number of students living in the county and attending public schools, regardless of which school they attend.
| School District | Students Residing in Tazewell County | Payment Breakdown | School Percentage |
|---|---|---|---|
| District 50 | 549 | $648,654 | 2.92% |
| Central 51 | 1269 | $1,499,347 | 6.75% |
| Washington 52 | 808 | $954,667 | 4.30% |
| Creve Coeur 76 | 427 | $504,509 | 2.27% |
| Robein 85 | 138 | $163,050 | 0.73% |
| East Peoria 86 | 1387 | $1,638,767 | 7.38% |
| Rankin 98 | 201 | $237,485 | 1.07% |
| NPMH 102 | 459 | $542,317 | 2.44% |
| Pekin 108 | 3115 | $3,680,431 | 16.58% |
| South Pekin 137 | 186 | $219,763 | 0.99% |
| Pekin 303 | 1724 | $2,036,938 | 9.18% |
| WCHS 308 | 1353 | $1,598,595 | 7.20% |
| East Peoria 309 | 845 | $998,383 | 4.50% |
| Spring Lake 606 | 55 | $64,984 | 0.29% |
| Deer Creek – Mackinaw 701 | 896 | $1,058,641 | 4.77% |
| Tremont 702 | 859 | $1,014,925 | 4.57% |
| Delavan 703 | 359 | $424,165 | 1.91% |
| Morton 709 | 3228 | $3,813,943 | 17.18% |
| Hartsburg Emden 21 | 0 | $0 | 0.00% |
| Illini Central 189 | 17 | $20,086 | 0.09% |
| Midwest Central 191 | 343 | $405,261 | 1.83% |
| Olympia 16 | 510 | $602,575 | 2.71% |
| Germantown 69 | 0 | $0 | 0.00% |
| Metamora High 122 | 0 | $0 | 0.00% |
| Eureka 140 | 62 | $73,254 | 0.33% |
| Totals | 18,790 | $22,200,739 | 100.00% |
Yes. Revenue would be generated from people who live outside of Tazewell County. Any person who is visiting or traveling through the county and makes a purchase that qualifies would contribute to the revenue for local schools.
It is estimated that nearly 60% of all purchases in Tazewell County are made by non-residents, according to a 2026 analysis by PGAV Planners.
If approved, Tazewell County would join all of its neighboring counties that are investing in their schools through a CSFT.
Shall a retailers’ occupation tax and a service occupation tax (commonly referred to as a sales tax) be imposed in The County of Tazewell, Illinois, at a rate of 1% to be used exclusively for school facility purposes, school resource officers, and mental health professionals?
Election day is Tuesday, November 3, 2026. Polls are open 6:00 a.m. to 7:00 p.m. on Election Day. Early voting is available starting September 24. For details about how to vote, including voting locations and how to register, visit www.elections.il.gov.
To learn more, contact your local school district by visiting their website or attend an upcoming informational meeting.